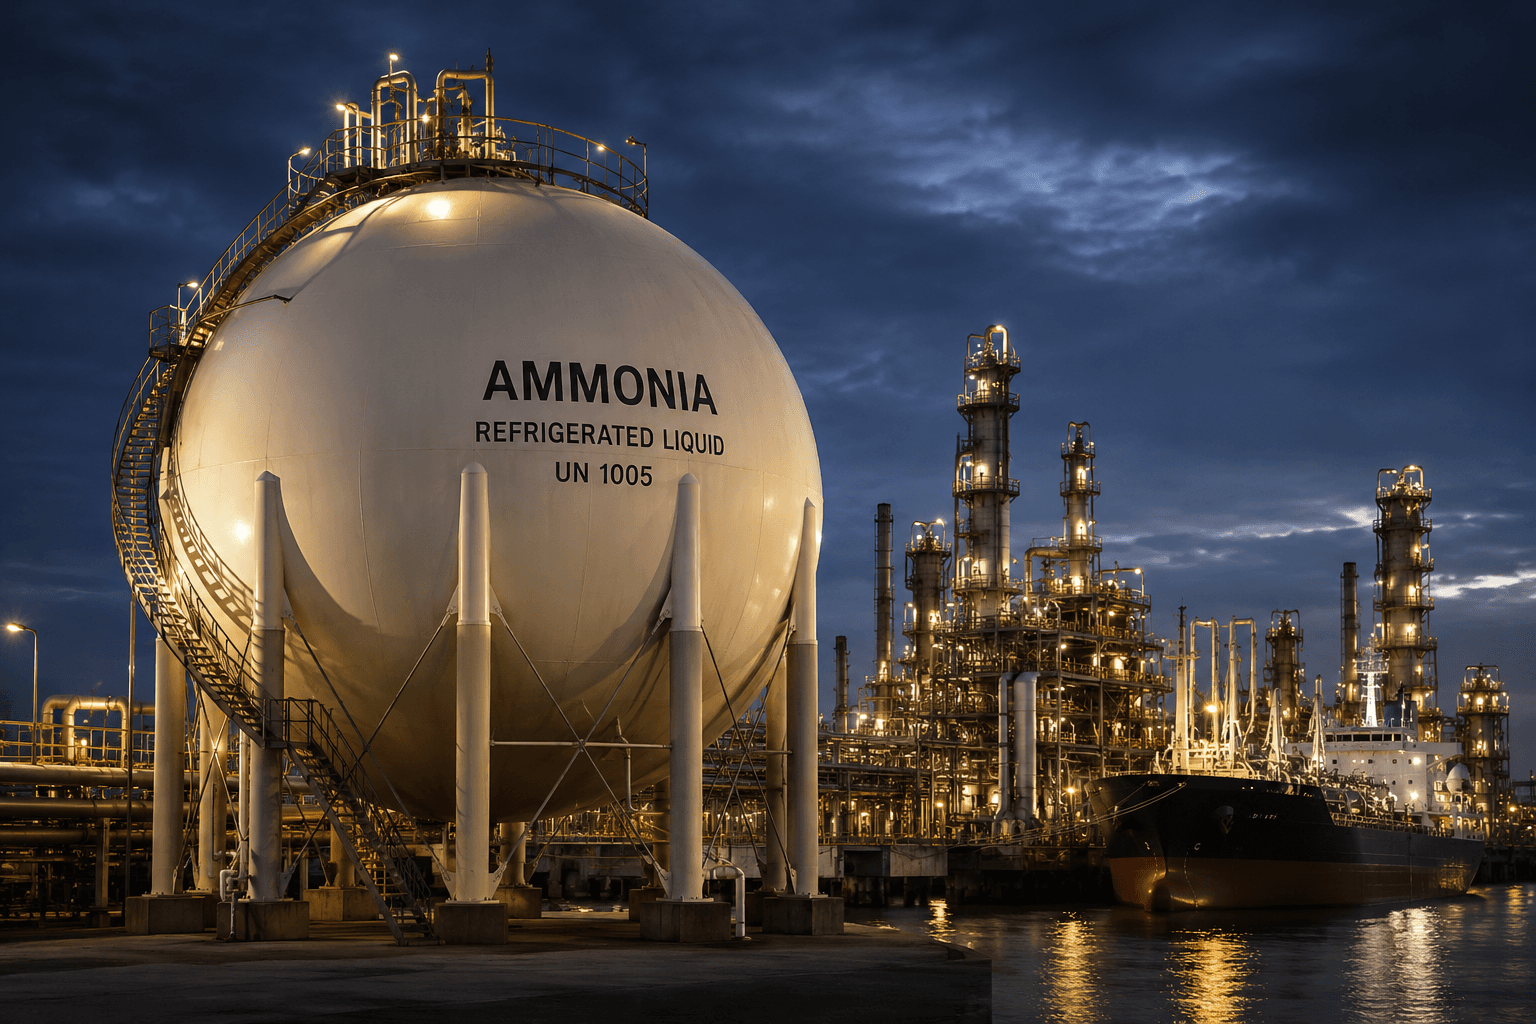
The global ammonia market entered 2026 with already tight supply conditions, but the simultaneous shutdown of Iranian production and QatarEnergy's force majeure transformed a challenging market into a major procurement crisis. Two of the region's most important fertilizer exporters experienced disruptions at the same time, removing significant volumes from international trade.
For ammonia buyers, the consequences have been immediate. Supply availability has tightened, replacement cargoes have become more difficult to secure and price expectations remain elevated. Market participants increasingly view the current disruption as one of the most significant fertilizer supply shocks in recent years.
Why Iran's Production Halt Matters
Iran occupies an important position within the global ammonia trade.
As a major exporter, Iranian production supports fertilizer manufacturers, industrial consumers and agricultural supply chains across multiple regions. When production halted during the conflict, buyers immediately lost access to a substantial source of internationally traded ammonia.
The impact became even more significant because the disruption occurred alongside production issues elsewhere in the Middle East.
Several consequences emerged rapidly:
Export availability declined sharply.
Buyers competed for replacement supply.
Spot market liquidity weakened.
Freight demand shifted toward alternative origins.
Price expectations moved higher across nitrogen markets.
The loss of Iranian production alone would have influenced global trade flows. Combined with disruptions elsewhere, the effect became far more pronounced.
The Double Impact of Iran and Qatar Supply Losses
The fertilizer market rarely experiences simultaneous disruptions involving multiple major exporters.
The shutdown of Iranian ammonia production occurred while QatarEnergy maintained force majeure conditions affecting ammonia and downstream fertilizer exports. Together, these events removed significant volumes from a market that was already facing logistical and geopolitical uncertainty.
This combination created a powerful supply shock.
Importers that previously relied on Middle East cargoes suddenly found themselves searching for alternative suppliers. Traders responded by securing available volumes wherever possible, further tightening market conditions.
The resulting pressure extended beyond ammonia itself and influenced broader nitrogen fertilizer markets.
Why Prices Remain Elevated
The ammonia market entered the crisis from a relatively balanced position, but supply losses quickly altered market sentiment.
Earlier contract settlements in major benchmark markets already reflected firm fundamentals. Once Middle East production disruptions emerged, expectations shifted toward prolonged tightness rather than temporary shortages.
Several factors continue supporting elevated pricing:
Reduced export availability.
Increased procurement competition.
Higher logistics uncertainty.
Limited immediately available replacement volumes.
Continued demand from fertilizer producers.
Because ammonia serves as a key feedstock for multiple fertilizer products, supply disruptions can influence pricing across the broader agricultural nutrient sector.
Sulfur Markets Add Another Layer of Pressure
The ammonia market does not operate in isolation.
The same disruption affecting nitrogen fertilizers has also influenced sulfur markets, creating additional challenges across the fertilizer industry. Market observers have emphasized the strategic importance of sulfur trade flows moving through affected shipping channels.
This matters because sulfur plays a critical role in phosphate fertilizer production.
When sulfur supply becomes uncertain, phosphate production costs rise. This creates simultaneous pressure across nitrogen and phosphate markets, amplifying the overall impact on agricultural input costs.
The result is a fertilizer environment where multiple nutrients face upward pricing pressure at the same time.
Alternative Supply Regions Gain Importance
Procurement teams have responded by accelerating supplier diversification efforts.
Many buyers are reducing dependence on Middle East sources and increasing engagement with producers located in other export regions. This shift reflects both immediate supply needs and longer-term risk management objectives.
The most closely watched alternative origins include:
US Gulf producers.
Black Sea suppliers.
North African exporters.
Selected Asian production hubs.
These regions have become increasingly important as buyers seek stable supply channels and reduced geopolitical exposure.
The US Gulf Opportunity
The US Gulf has emerged as one of the most attractive alternative sourcing regions.
Strong infrastructure, established export capabilities and access to competitively priced feedstocks support the region's role within international ammonia trade. Buyers seeking dependable supply increasingly view US Gulf producers as an important component of diversification strategies.
Advantages include:
Established export logistics.
Large-scale production capacity.
Strong commercial transparency.
Broad international market access.
Although US supply cannot fully replace every lost Middle East cargo, it provides an important source of stability during periods of disruption.
Why North Africa Is Attracting More Attention
North African producers have also gained visibility as procurement teams reassess sourcing strategies.
The region offers geographic advantages for multiple destination markets and maintains established fertilizer export infrastructure. As buyers look beyond traditional Middle East supply channels, North Africa continues to strengthen its position within global fertilizer trade.
Many trading companies now evaluate North African suppliers as part of broader portfolio diversification plans rather than as occasional alternative sources.
This shift could have lasting implications even after current disruptions ease.
What Procurement Teams Should Do Immediately
The current ammonia market environment requires proactive risk management.
Waiting for supply conditions to normalize may expose buyers to continued volatility and procurement challenges. Organizations that act early often secure greater flexibility than those reacting after market conditions tighten further.
Priority actions include:
Expanding approved supplier networks.
Evaluating alternative sourcing regions.
Increasing market intelligence monitoring.
Reviewing inventory policies.
Assessing exposure to single-origin procurement strategies.
Strengthening contingency planning.
These measures can help reduce operational risk while improving supply resilience.
The Outlook for Global Ammonia Markets
Ammonia markets are likely to remain sensitive to developments across the Middle East throughout the remainder of 2026. Even if production resumes, restoring export volumes, shipping confidence and commercial activity will require time.
The simultaneous disruption of Iranian and Qatari supply has reinforced the importance of diversification in fertilizer procurement. Companies that broaden sourcing beyond traditional supply hubs will be better positioned to navigate future disruptions and manage price volatility.
For ammonia buyers, the market has entered a period where supply security carries as much importance as price. The organizations that recognize this shift early are likely to gain a competitive advantage as global fertilizer trade continues to evolve.
Ready to source Ammonia Anhydrous from verified global suppliers? Explore competitive offers on our platform today.
Ammonia Anhydrous CAS: 7664-41-7