
Urea (Granular) - Egypt CAS: 57-13-6
Urea (Granular) - Egypt CAS: 57-13-6
German chemical capacity utilization improved slightly to 75.1% but remains below the level needed for profitable production. With VCI expecting output to fall again across 2026, procurement teams should prepare for restructuring, reduced local availability and greater import dependence.
Thousands of vessels stranded in the Persian Gulf during the 2026 disruption created unexpected demand for water treatment and vessel maintenance chemicals. As shipping resumes, fleet inventory replenishment is expected to drive strong Q3 procurement activity.
FACT India’s new 2026 ammonia tender marks a decisive move toward formula‑linked contracts, offering stability in a market plagued by volatile fertilizer prices. This long‑duration deal signals a strategic shift in fertilizer procurement, providing a predictable pricing framework for the next decade.
Pharmaceutical solvent markets are entering H2 2026 with improving feedstock economics and stabilizing crude oil prices. This creates an ideal procurement window for pharmaceutical manufacturers to secure long-term solvent supply agreements before potential market volatility returns.
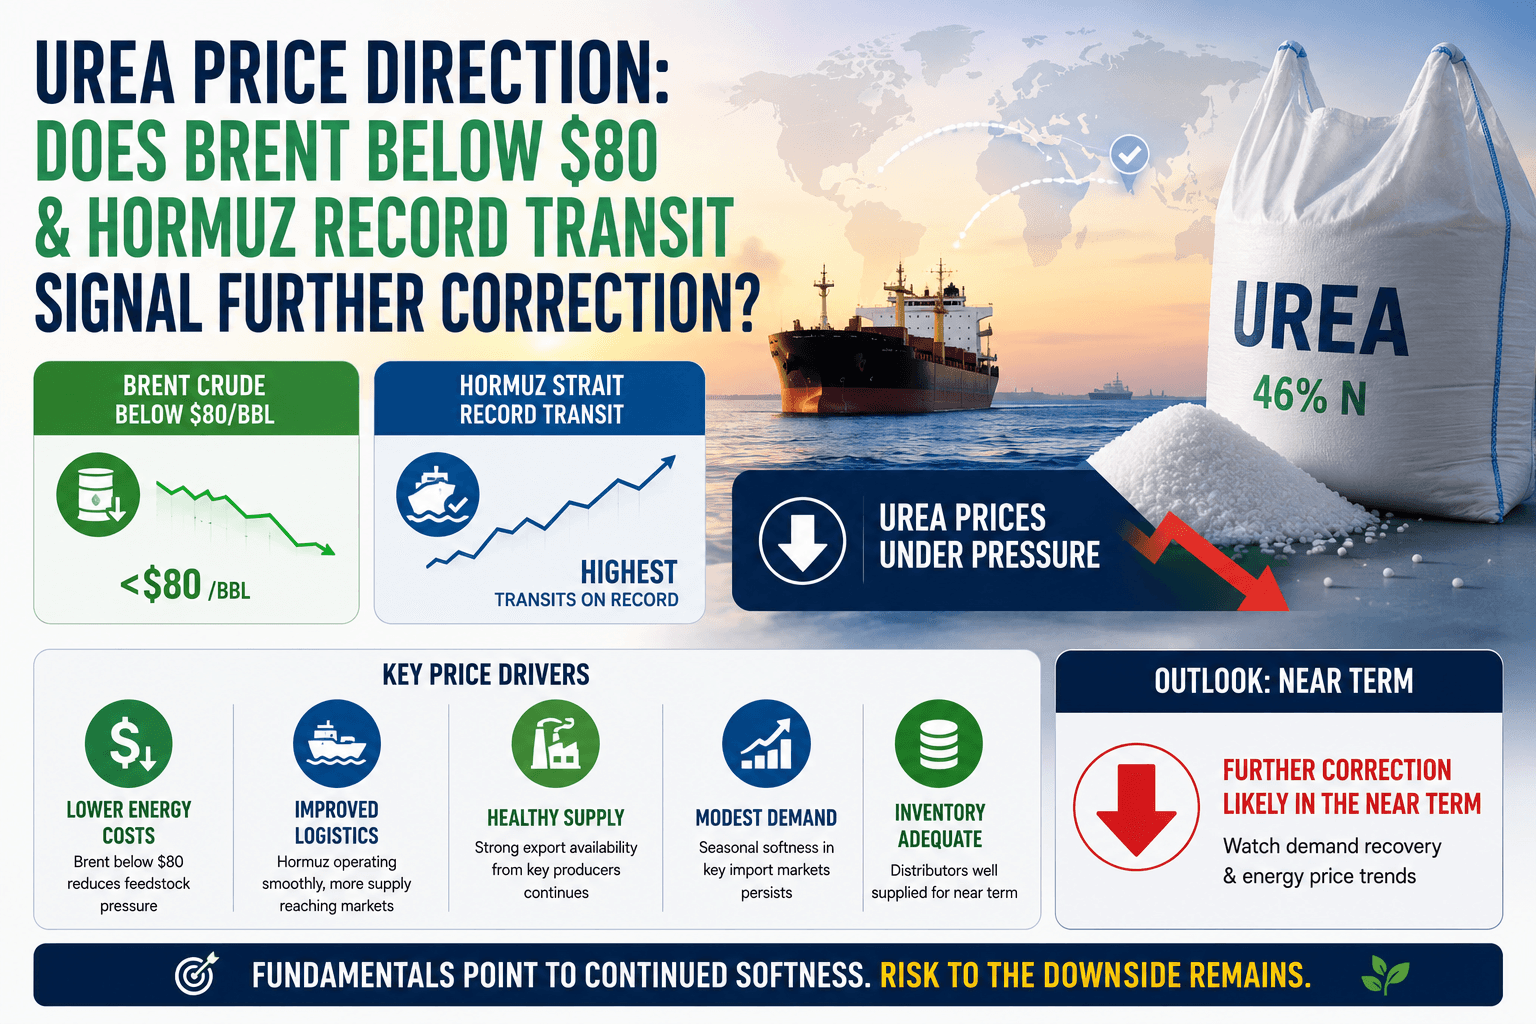
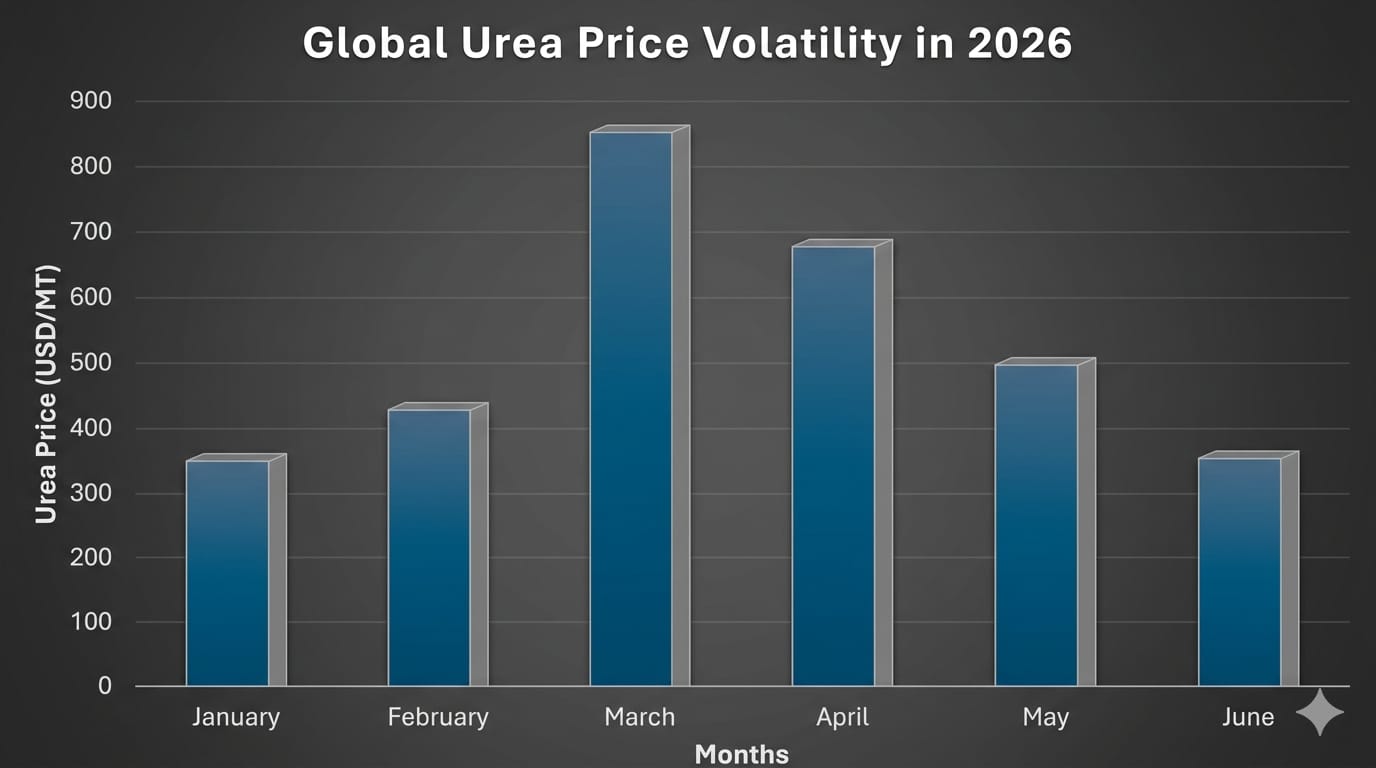
Urea prices have already fallen 36% from April highs, but improving Hormuz shipping and lower Brent crude suggest only modest further correction ahead. For fertilizer buyers, the strongest buying opportunity may already be unfolding before Q3 market stabilization begins.

Thai sorbitol production is tightening as the annual tapioca feedstock gap reduces output, while Chinese suppliers continue operating at stable capacity with competitive export pricing. Procurement teams planning H2 2026 purchases have a valuable opportunity to lock in improved delivered costs before seasonal market dynamics shift again.
We're committed to your privacy. Tradeasia uses the information you provide to us to contact you about our relevant content, products, and services. For more information, check out our privacy policy.