For LNG traders, petrochemical buyers and energy market analysts, June 23 represents one of the most closely watched dates in the Asia-Pacific energy sector.
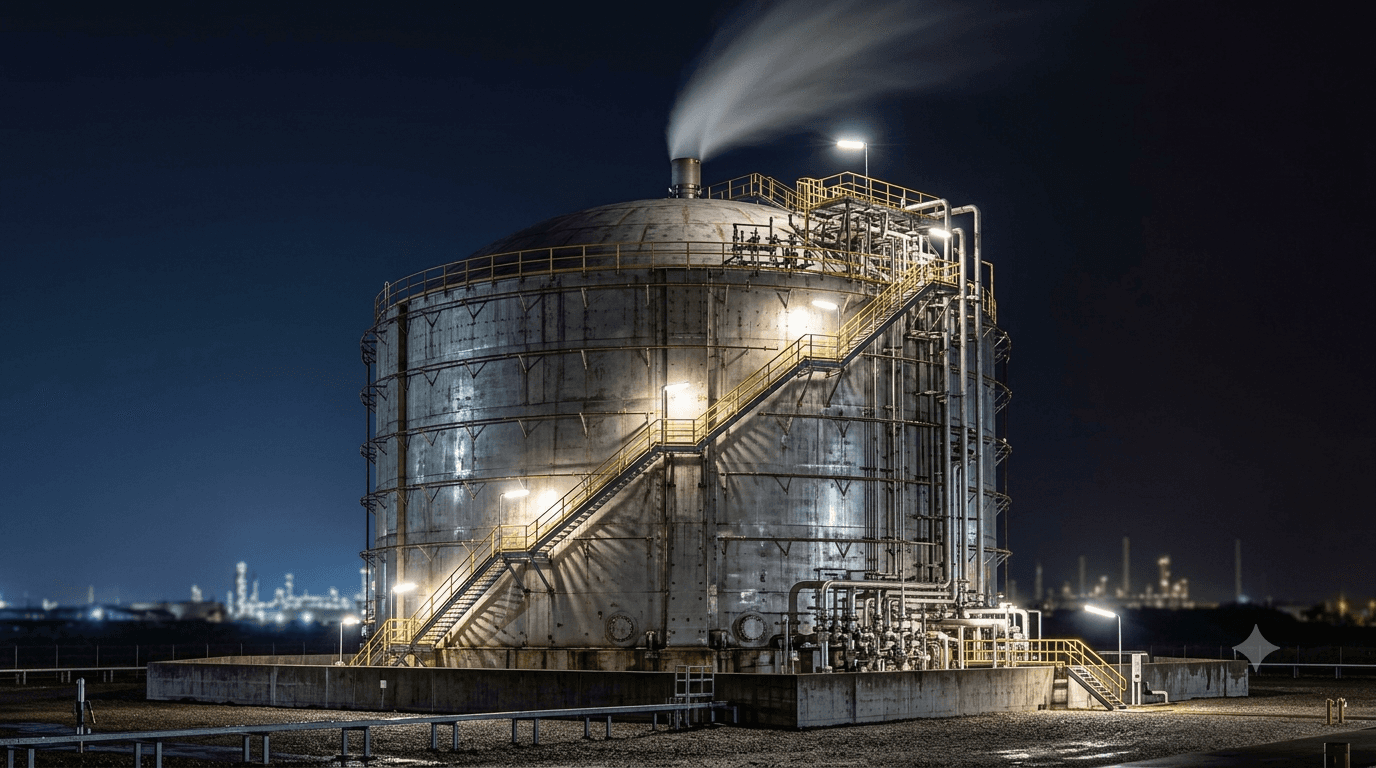
The protected industrial action affecting the Ichthys LNG project in Darwin, Australia has become a significant source of uncertainty for both LNG and condensate markets. While the facility has largely continued operating, ongoing labor disputes have created concerns about future loading schedules, export reliability and feedstock availability.
As the authorized industrial action period reaches its latest milestone, market participants are seeking answers to a critical question:
Will the dispute finally be resolved, or will operational uncertainty continue into the second half of 2026?
Why Ichthys Matters
The Ichthys project is one of Australia's most important LNG export facilities.
The project supplies significant volumes of:
Liquefied Natural Gas (LNG)
Condensate
LPG products
These exports serve major customers throughout Asia, particularly in:
Japan
South Korea
Taiwan
Southeast Asia
As a result, any operational disruption quickly attracts attention from both energy and chemical markets.
The Labor Dispute Explained
The industrial action centers on disagreements between INPEX and labor unions representing workers at the facility.
Key issues have reportedly included:
Workforce arrangements
Replacement personnel policies
Employment conditions
Operational staffing concerns
The dispute escalated into protected industrial action that included restrictions affecting loading operations.
While production has not experienced a complete shutdown, the possibility remained a major concern for market participants.
Why LNG Buyers Are Watching Closely
The primary concern remains LNG supply.
Japanese utilities and Asian energy buyers depend on reliable LNG imports to support:
Electricity generation
Industrial energy demand
Energy security planning
Even modest supply disruptions can influence:
Spot LNG pricing
Procurement strategies
Storage planning
Alternative sourcing decisions
This explains why LNG buyers have been closely monitoring developments throughout the dispute.
Condensate Is the Chemical Market Story
While LNG receives most of the headlines, chemical market participants are paying close attention to another product:
Condensate.
Condensate is a valuable hydrocarbon stream that serves as an important feedstock for:
Naphtha production
Petrochemical crackers
Refining operations
Aromatics production
Asian petrochemical producers rely on stable condensate supplies to support downstream manufacturing.
Any reduction in exports can affect feedstock economics throughout the region.
Why Naphtha Crackers Care
Condensate ultimately influences one of Asia's most important petrochemical feedstock chains.
Condensate can be processed into:
Naphtha
Light hydrocarbons
Petrochemical feedstocks
These materials support production of:
Ethylene
Propylene
Polyethylene
Polypropylene
Aromatics
Although LNG buyers remain the most exposed group, petrochemical companies are also monitoring developments carefully.
The Fair Work Commission's Role
The labor dispute attracted additional attention after regulatory intervention failed to bring an immediate resolution.
The decision not to terminate industrial action earlier in the year left open the possibility of continued operational restrictions.
As a result, markets have spent months evaluating various scenarios, including:
Full resolution
Partial resolution
Extended industrial action
Escalation into broader operational disruption
This uncertainty has become a key market variable.
What Happens if the Dispute Is Resolved?
A successful agreement would likely support:
LNG Supply Stability
Reduced concerns about export reliability.
Improved Buyer Confidence
Lower perceived supply risk.
Condensate Flow Normalization
More predictable feedstock availability.
Freight Market Stability
Reduced uncertainty for cargo scheduling.
Such an outcome would be welcomed across both energy and chemical sectors.
What Happens if the Action Continues?
An extension would create a different set of risks.
Potential consequences include:
Loading Delays
Cargo scheduling could remain unpredictable.
Reduced Export Volumes
Some shipments could face disruption.
Higher Market Risk Premiums
Buyers may increase contingency planning.
Feedstock Concerns
Condensate consumers may seek alternative sources.
The market impact would depend on the duration and severity of any continued action.
Procurement Implications for Chemical Buyers
Companies dependent on condensate-linked feedstocks should consider several actions.
Monitor Supplier Communications
Official updates remain critical.
Review Feedstock Exposure
Identify products reliant on condensate-derived materials.
Assess Alternative Supply Options
Diversification may reduce risk.
Track Naphtha Markets
Feedstock pricing often reacts quickly to supply concerns.
Maintain Supply Chain Visibility
Understanding upstream dependencies is increasingly important.
These steps can improve resilience while uncertainty persists.
What to Watch Next
Several indicators will determine the significance of the outcome.
Union Announcements
Negotiation updates will provide immediate signals.
INPEX Statements
Operational guidance remains critical.
LNG Loading Schedules
Export performance will reveal actual supply conditions.
Condensate Cargo Availability
A key metric for petrochemical markets.
Asian Spot Market Reactions
Pricing behavior often reflects perceived supply risk.
Together, these indicators will determine whether the issue fades quickly or remains a market concern.
Conclusion
The June 23 milestone at Australia's Ichthys LNG facility is important not only for LNG buyers but also for chemical market participants dependent on condensate-derived feedstocks. While the dispute has not caused a full operational shutdown, ongoing uncertainty has kept energy and petrochemical markets on alert.
For LNG importers, the priority remains supply security and export reliability. For chemical producers, the focus is condensate availability and its downstream impact on naphtha and petrochemical feedstocks.
Whether the dispute is resolved immediately or extends further, the Ichthys situation highlights a broader reality of 2026: labor relations, logistics and feedstock availability are increasingly interconnected risks that procurement teams must monitor as closely as traditional commodity pricing.
2-Ethyl Hexanol CAS: 104-76-7